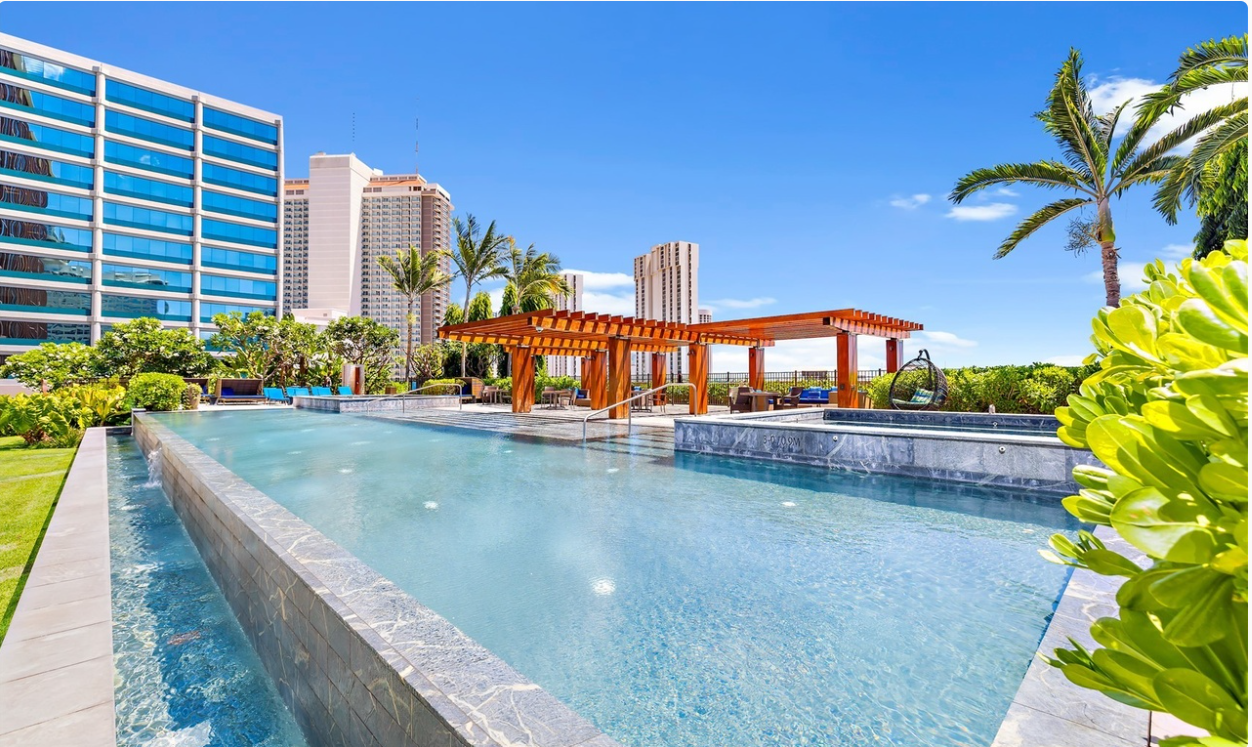
One Ala Moana
1555 Kapi’olani Boulevard #2301, Honolulu, Hawaii 96814
Private Capital Memo
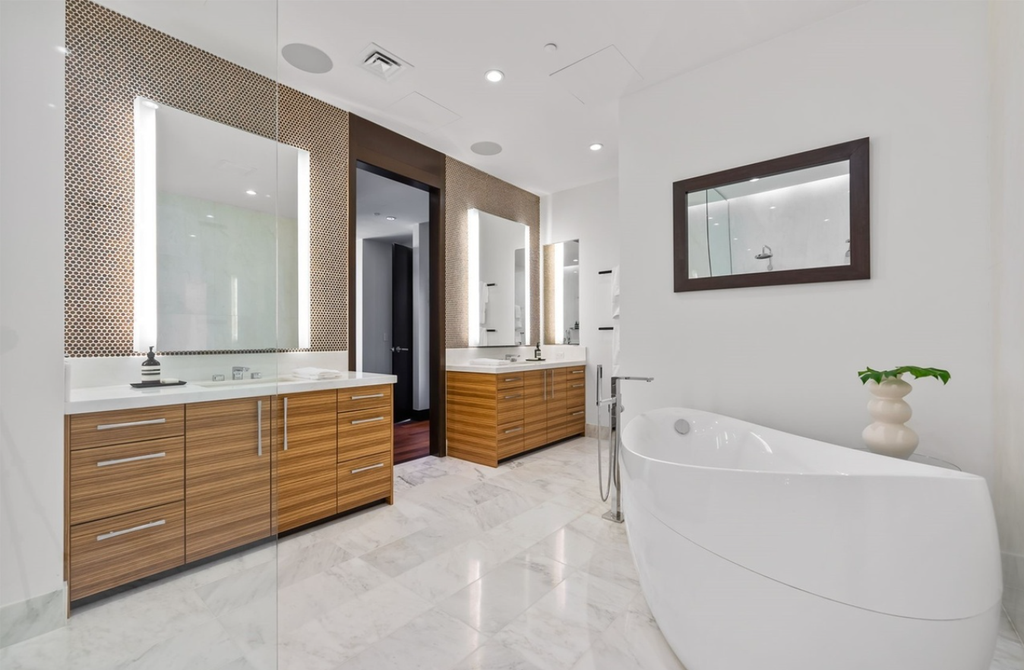
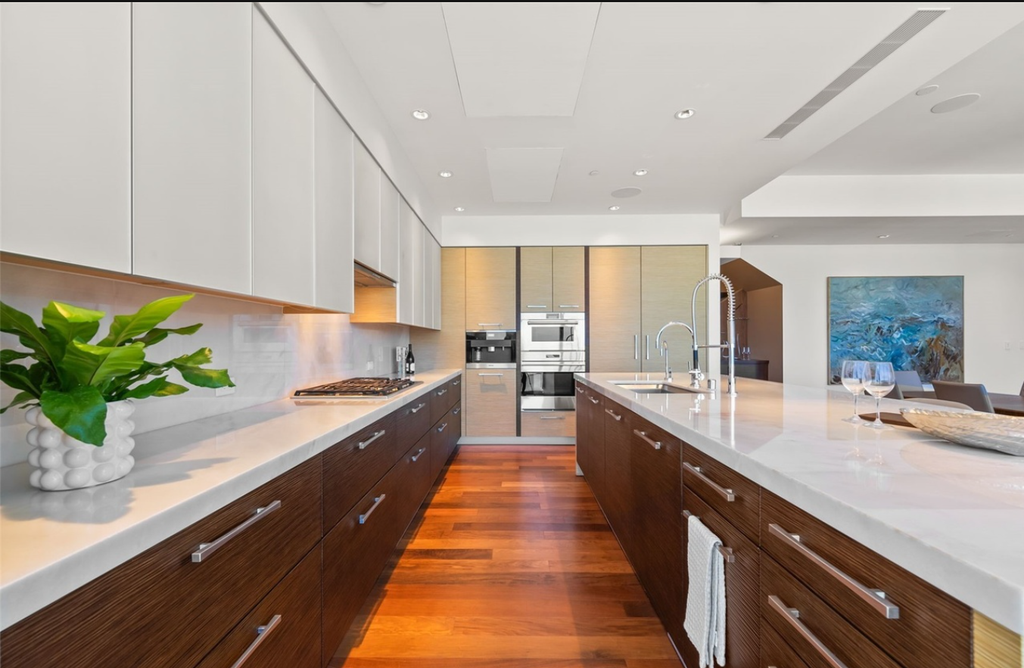
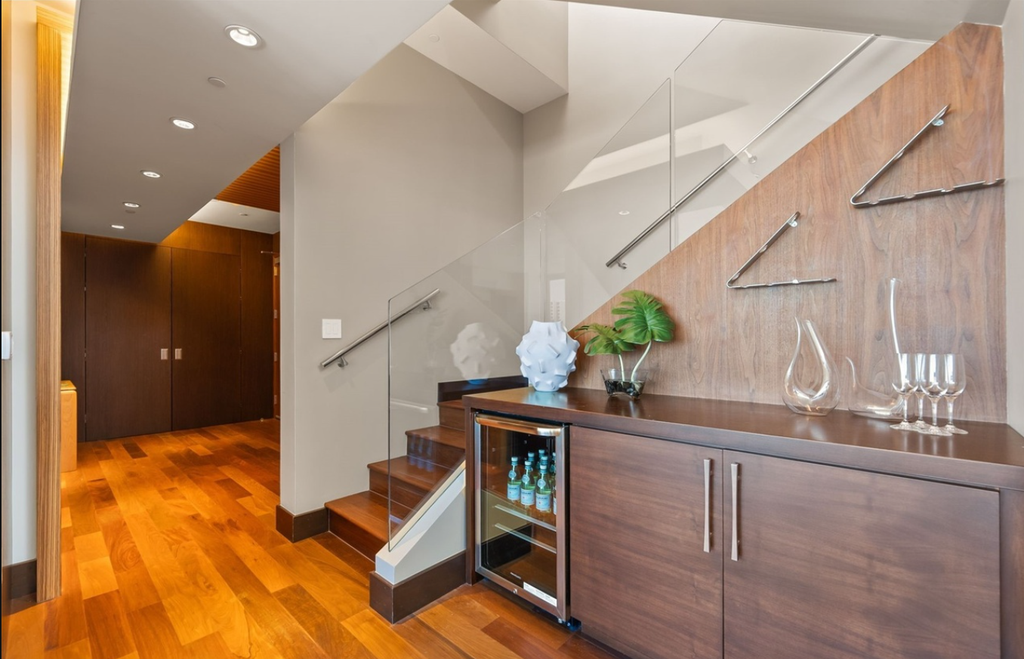
This is not a rendering. This is the asset. Floor 23. One Ala Moana. The tenant who needs this already knows what they’re looking at. So does the right capital partner.
THE DEAL SNAPSHOT
| Line Item | Amount |
|---|---|
| Total Capital Deployed | $7,130,000 |
| Flat 10% Total Return | $713,000 |
| Total Funder Recovery Target | $7,843,000 |
| Funder Monthly Distribution (Accumulation Phase) | $37,361 |
| Funder Monthly Distribution (Post-Reserve Cap) | $48,331 |
| Operator Monthly Distribution (Accumulation Phase) | $9,340 |
| Operator Monthly Distribution (Post-Reserve Cap) | $12,083 |
| Months to Full Recovery | ~165 months |
| Estimated Full Recovery Timeline | ~13.75 years |
One capital partner. One asset. One revenue stream.
THE ASSET
One private rooftop. Three parking stalls. One tenant profile that will always exist and always need exactly this.
No comparable inventory in the Kakaako vertical luxury market at this specification. The supply constraint is not a talking point. It is the market condition.
THE NUMBERS
| Accumulation Phase | Post-Reserve Cap | |
|---|---|---|
| Gross Monthly | $90,000 | $90,000 |
| Less Carrying Costs | ($27,586) | ($27,586) |
| Less Maintenance Reserve | ($2,000) | ($2,000) |
| Less Operating Reserve | ($13,713) | — |
| Net Available | $46,701 | $60,414 |
| Funder (80%) | $37,361 | $48,331 |
| Operator (20%) | $9,340 | $12,083 |
This is not a projected return. It is a defined one. $7,130,000 deployed. $7,843,000 recovered. A flat 10% total return distributed monthly across approximately 14 years — secured against a hard asset in one of the most supply-constrained luxury residential markets in the United States.
Baseline income model based on $90,000 gross monthly rental income, validated by three independent market comparables. Hawaii GET (4.712%, inclusive of Oahu county surcharge) and TAT (13.25%) applied to gross. Total carrying costs ~$27,586/month inclusive of HOA, property taxes, professional cleaning, GET, and TAT. A $2,000 monthly maintenance reserve and $13,713 monthly operating reserve are each deducted prior to net revenue calculation and held in dedicated accounts. The maintenance reserve is capped at $24,000. The operating reserve is capped at $164,556 (twelve months of fixed carrying costs). Net rental income during accumulation phase ~$46,701 (funder ~$37,361, operator ~$9,340). Once both reserve caps are reached, deductions cease and distributions return to ~$60,414 net (funder ~$48,331, operator ~$12,083) until either reserve is drawn below cap, at which point contributions resume.
THE MARKET
$90,000/month is not a projection.
It is a discount to every comparable in the submarket. The Ritz-Carlton charges $87,000/month for an inferior product on a lower floor with shared amenities and no private outdoor space. Espacio prices an equivalent nightly stay at $180,000/month equivalent. The in-building precedent establishes $18,000/month as the floor for a lesser unit in the same tower.
Floor 23 is none of those things. It is the only unit that can deliver what this tenant profile requires — and there is no comparable inventory to compete with it.
FULL RECOVERY TIMELINE
| Amount | |
|---|---|
| Funder Recovery Target | $7,843,000 |
| Year 1 Recovery (12 × $37,361) | $448,332 |
| Remaining Balance After Year 1 | $7,394,668 |
| Months to Full Recovery at $48,331 | ~153 months |
| Total Estimated Recovery Timeline | ~165 months (~13.75 years) |
MARKET VALIDATION
The Market Has Already Priced This Asset
$90,000/month is not a projection. It is a discount to every comparable in the market.
COMP ONE
Floor 20 — One Ala Moana In-Building Rental Precedent
A 3-bedroom unit on Floor 20 — same tower, lower floor, no rooftop, two parking stalls — is currently leased at $18,000/month.
Floor 23 is a 4-bedroom full-floor penthouse with 1,900 sq ft of private rooftop and three parking stalls.
Floor 20 has none of that.
The in-building precedent establishes $18,000/month as the floor for a lesser unit in the same tower. Floor 23 is not a lesser unit.
COMP TWO
Ritz-Carlton Residences, Waikiki Luxury Hospitality Benchmark — $87,000/month
The Ritz-Carlton delivers hotel infrastructure and shared amenities. No private outdoor space at scale. No full-floor exclusivity. No parking embedded in the asset.
Floor 23 delivers what the Ritz cannot replicate — at a 3% premium to an inferior hospitality product.
$90,000/month is the conservative number in this comparison.
COMP THREE
Espacio — Penthouse Diamond Suite Nightly Rate Benchmark — $6,000/night
At 30 nights: $180,000/month equivalent. At 80% occupancy: $144,000/month.
Floor 23 delivers 2.6x the square footage, a 1,900 sq ft private rooftop, full-floor exclusivity, and three dedicated parking stalls — at a product Espacio cannot replicate.
Our $90,000/month target is priced at 50% of the Espacio nightly equivalent on a significantly superior asset.
COMP FOUR
Kakaako Market — Dedicated Parking Stalls Embedded Asset Value — $100,000/stall
Three stalls included in the $6,780,000 acquisition price.
$300,000 in embedded parking value is inside the acquisition cost. The parking alone represents 4.4% of total deployment at current Kakaako market rates.
COMPARISON TABLE
| Comparable | Monthly Rate | Product |
|---|---|---|
| Floor 20 — One Ala Moana | $18,000 | 3BD, no rooftop, two stalls |
| Ritz-Carlton Residences | $87,000 | Shared amenities, no private outdoor |
| Espacio Diamond Suite | $180,000+ | 2BD, 2,250 sq ft, no parking |
| Floor 23 — Our Target | $90,000 | 4BD, 1,900 sq ft rooftop, 3 stalls |
The market has already validated this asset class.We are entering at the intersection of two proven demand pools — extended-stay luxury residential and Pacific Rim executive housing — in a supply-constrained submarket with no comparable inventory.
$90,000/month is where the market already is. Floor 23 is simply the only unit that can deliver it.
THE STRUCTURE
A Revenue Participation Agreement. Not a loan. Not equity. Not a partnership.
| Capital Ask | $7,130,000 |
| Acquisition | To be confirmed |
| Furnishing Budget | To be confirmed |
| Split | Flat 80/20 in funder’s favor |
| Step-down | None. 80/20 the entire way through. |
| Structure | Revenue Participation Agreement — not a loan, not equity |
| Recourse | Zero personal recourse |
WHAT THIS IS
The funder provides capital in exchange for a defined percentage of net rental income generated by the asset.
No equity transfer. No partnership formation. No personal guarantee. No debt obligation created against the operator personally. The operator retains full legal title to the asset.
The funder holds a contractual right to revenue — secured against the asset itself, not the person behind it.
RECOURSE
Zero personal recourse to the operator.
The funder’s sole recourse is against the asset — not the operator’s personal income, personal assets, or other holdings. If the property generates no net rental income in a given period, the revenue participation suspends until income resumes.
A revenue participation agreement is not a guarantee of return. It is a share of documented income. The distinction is non-negotiable.
OPERATOR ALIGNMENT
The operator receives income only when the funder receives income.
A vacant month costs the operator $12,083 in lost personal income. The operator’s financial self-interest and the funder’s financial self-interest are identical.
That is not a clause in a contract. That is the structure itself.
YOUR PROTECTIONS
| Protection | Detail |
|---|---|
| Revenue Claim | Priority claim on all net rental income — distributions to funder precede any operator compensation |
| Reporting | Monthly — within 5 business days of month close |
| Distribution | Monthly — within 10 business days of month close |
| Audit Rights | Any time — 10 business days written notice |
| Asset Sale Protection | Funder made whole from proceeds before operator realizes any gain |
| Title Recording | RPA or equivalent security instrument to be structured in consultation with a Hawaii real estate attorney prior to contract execution |
No black box. No chasing. No wondering where your money is.
Reports and distributions arrive on a fixed schedule every month. Every month you can see exactly where you are in the recovery timeline.
This memorandum is an invitation to a conversation, not a binding instrument. All structural, legal, and tax terms — including the specific security mechanism recorded against title — will be confirmed and documented by a Hawaii real estate attorney and CPA prior to contract execution. Nothing in this memo constitutes a legal obligation by either party.
MAINTENANCE RESERVE
A monthly maintenance reserve of $2,000 is deducted from gross rental income prior to the net revenue calculation and held in a dedicated reserve account. This reserve is not distributed to either party.
The reserve accumulates to a maximum of $24,000. Once the $24,000 cap is reached, the monthly $2,000 deduction ceases and net rental income returns to the full baseline calculation until the reserve is drawn down below the cap threshold — at which point monthly contributions resume until the cap is restored.
Reserve funds are used exclusively for asset maintenance, repair, and condition preservation. Any expenditure from the reserve exceeding $5,000 is documented and reported to the funder within 5 business days.
Unused reserve funds at agreement termination are distributed to the operator.
OPERATING RESERVE
An operating reserve of $164,556 (twelve months of fixed carrying costs) is funded via monthly contribution of $13,713 taken prior to distribution. Once the target is reached, contributions pause and full net revenue enters the participation split. Contributions resume only if the reserve is drawn below threshold.
The operating reserve exists to ensure uninterrupted coverage of fixed carrying costs during vacancy periods, ownership transitions, or unforeseen revenue disruptions. It is held separately from the maintenance reserve and is not commingled with distribution funds.
Fixed carrying costs covered by this reserve include HOA dues, property taxes, homeowner’s insurance, and base utilities. Variable costs including professional cleaning, General Excise Tax, and Transient Accommodations Tax are excluded from the reserve calculation as they are incurred only during occupied revenue-generating periods.
Unused operating reserve funds at agreement termination are retained by the operator.
PET FEES
Pet fees are non-refundable and deposited directly into the maintenance reserve fund. They do not flow through the revenue participation split. Pet fees exist to offset pet-related wear and damage beyond standard turnover and are held within the reserve until drawn for documented pet-related expenses. The $24,000 annual cap applies only to the standard $2,000 monthly contribution. Pet fees are additive to this structure and do not reset or replace the standard reserve contribution. Any unused pet fee balance at agreement termination is retained by the operator.
Pet fee structure to be confirmed in consultation with a Hawaii real estate attorney prior to contract execution.
EXIT SCENARIOS
In every exit scenario, the funder is made whole before the operator realizes any gain.
Full Capital Recovery — Upon cumulative distributions reaching $7,843,000, the RPA terminates automatically. The operator retains the asset free and clear. The funder exits with full principal returned plus a flat 10% total return on capital deployed.
Asset Sale Prior to Full Recovery — Funder receives their outstanding balance from sale proceeds at closing before any distribution to the operator. Funder is made whole from the transaction.
Operator Election to Refinance — Operator may elect to refinance at any point, using proceeds to retire the outstanding participation balance. Funder receives full remaining balance at that time.
WHAT THIS IS NOT
- Not a mortgage or personal loan
- Not an equity stake or ownership position
- Not a partnership or joint venture
- Not a personal guarantee
- Not a syndication
One asset. One revenue stream. One capital partner.
Clean math. Clean exit. Clean relationship
GOVERNANCE & REPORTING
You will always know exactly where your money is.
REPORTING SCHEDULE
| Report | Frequency | Delivery |
|---|---|---|
| Monthly Revenue + Occupancy Summary | Monthly | Within 5 business days of month close |
| Participation Distribution | Monthly | Within 10 business days of month close |
| Asset Condition Update | Quarterly | Within 10 business days of quarter close |
| Annual Summary Statement | Annual | Within 30 days of calendar year close |
WHAT EVERY MONTHLY REPORT INCLUDES
- Gross rental income received
- GET deducted (4.712% of gross — inclusive of Oahu county surcharge)
- TAT deducted (13.25% of gross)
- Itemized operating expenses
- Net revenue calculation
- Funder participation amount
- Operator draw amount
- Cumulative capital recovery to date
- Remaining balance outstanding
- Current occupancy status and tenant summary
Every month you can see exactly where you are in the recovery timeline. No calculating. No estimating. No chasing.
DISTRIBUTION MECHANICS
Funder participation is distributed via wire transfer to a designated account on file. Distribution instructions are established at closing and remain fixed unless the funder provides written notice of change with 10 business days lead time.
No distribution is held, delayed, or offset without written notice to the funder explaining the variance and the resolution timeline.
AUDIT RIGHTS
The funder retains the right to audit revenue records, expense documentation, and occupancy records at any time with 10 business days written notice.
The operator maintains clean, organized financial records accessible for audit within the notice period. Records retained for a minimum of 7 years.
The operator has nothing to hide. The audit right exists to confirm that — not because it will need to be exercised.
DISPUTE RESOLUTION
In the event of a dispute regarding revenue calculation, expense allocation, or distribution amounts:
- Parties engage in good faith written communication within 10 business days of dispute notice
- If unresolved, a mutually agreed neutral CPA reviews records — cost split equally unless a material discrepancy is found in the operator’s records, in which case the operator bears the full review cost
- If still unresolved, binding arbitration in Honolulu, Hawaii under JAMS arbitration rules
Disputes go to a neutral third party. Not a courtroom. Faster, cheaper, and cleaner for both parties.
OPERATOR PERFORMANCE STANDARDS
The operator commits to:
- Maintaining the asset in ultra-luxury condition consistent with the C-suite tenant profile at all times
- Sourcing qualified tenants exclusively at 29-day minimum tenancy — no short-term rental use
- Responding to tenant maintenance requests within 24 hours for urgent issues, 72 hours for non-urgent
- Notifying the funder within 5 business days of any vacancy anticipated to exceed 30 days
- Notifying the funder within 5 business days of any material asset issue exceeding $10,000 in estimated repair cost
WHAT THE FUNDER NEVER HAS TO DO
- Chase a report
- Wonder about occupancy
- Calculate their own return
- Request a distribution
- Manage anything
The operator runs the asset. The funder receives the income.
That is the entire relationship.
THE DECISION
You have seen the asset. You have seen the market. You have seen the structure. You have seen the math.
This is the summary.
WHAT YOU ARE BEING ASKED TO DEPLOY
$7,130,000
One capital partner. One asset. One revenue stream. Not syndicated. Not complicated.
WHAT YOU RECEIVE IN RETURN
| Metric | Figure |
|---|---|
| Monthly Income (Accumulation Phase) | $37,361 |
| Monthly Income (Post-Reserve Cap) | $48,331 |
| Annual Income (Accumulation Phase) | $448,332 |
| Annual Income (Post-Reserve Cap) | $579,972 |
| Total Return on Capital | 10% flat — $713,000 above principal |
| Total Funder Recovery | $7,843,000 |
| Full Capital Recovery Timeline | ~165 months (~13.75 years) |
| Personal Recourse to Operator | Zero |
| Equity Position Required | None |
| Management Required | None |
You deploy capital. You receive monthly income. You are made whole. You do nothing else.
YOUR PROTECTIONS — SUMMARY
Monthly reporting and distribution on a fixed schedule. Full audit rights at any time. Made whole in full before the operator realizes any gain — in every exit scenario. Zero personal recourse means your downside is the asset, not a person.
Revenue participation or equivalent security instrument recorded against the asset, to be confirmed with Hawaii counsel prior to execution.
THE ASK
One conversation. One decision. One capital partner who wants clean structure, monthly income, and a hard asset backing their capital.
If that is you — the next step is a conversation.
READY TO EXPLORE THIS OPPORTUNITY?
Start a conversation.
This page is a private, confidential summary for qualified capital consideration only. Not a securities offering. Full legal documentation prepared by counsel prior to closing.
mel.b@halehibiscus.com – (808) 583-4801