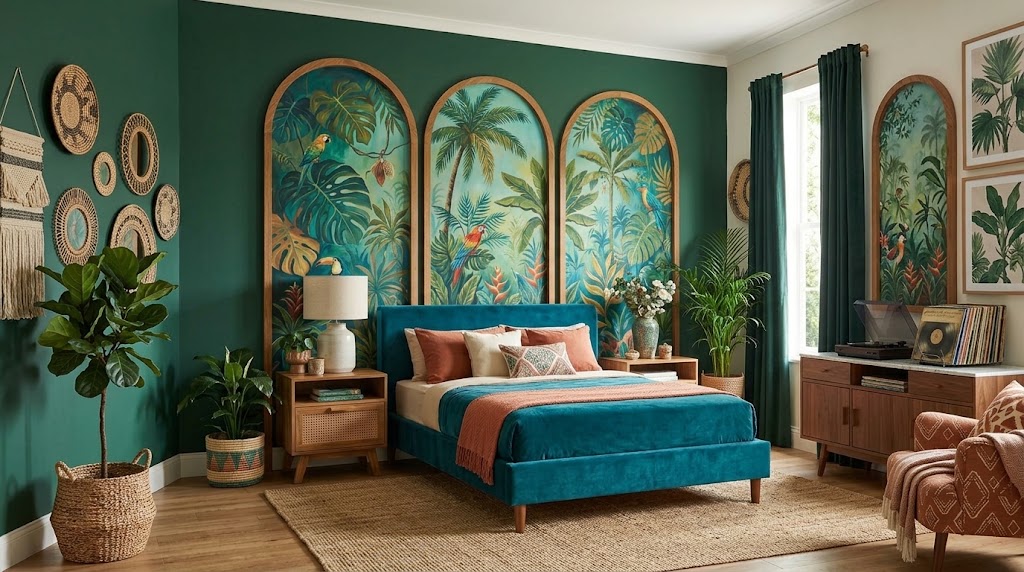
Ilikai Marina
1765 Ala Moana Boulevard #1699 Honolulu, HI 96815
Private Capital Memo
Deal Snapshot Card — Mid-Tier Unit
HALE HIBISCUS | MID OPPORTUNITY Premium short-term rental investment. Designed for the capital partner who wants meaningful returns at real scale — and a front-row view of the operator before the flagship conversation begins.
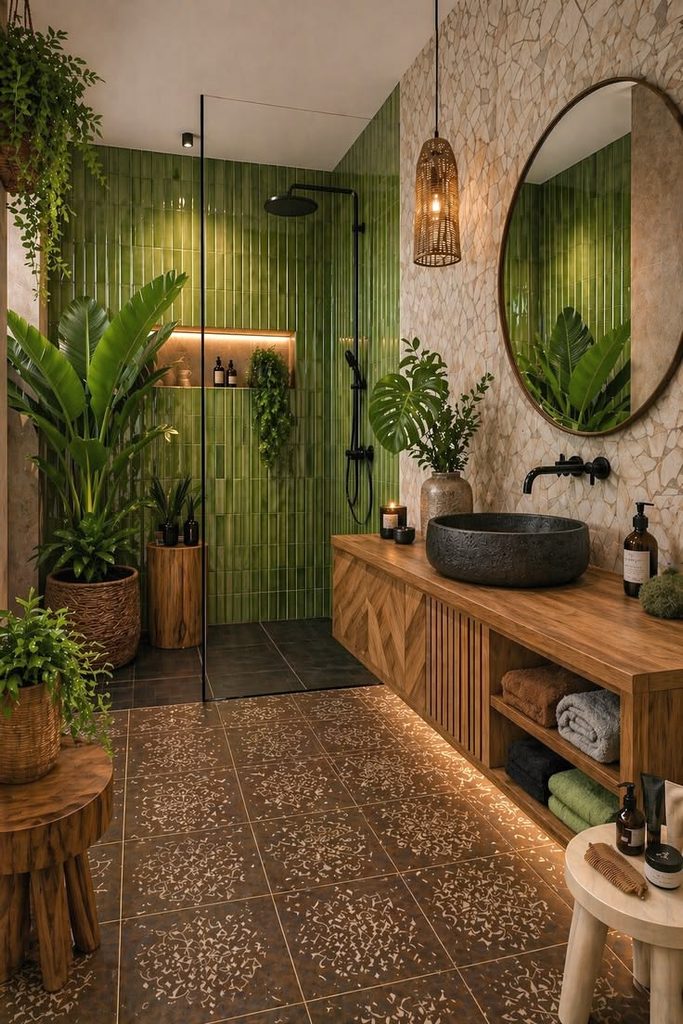
Proposed bathroom concept. Tropical luxury without the kitsch — living plants, warm wood, vessel sink, walk-in rainfall shower. The kind of bathroom guests photograph before they even unpack.
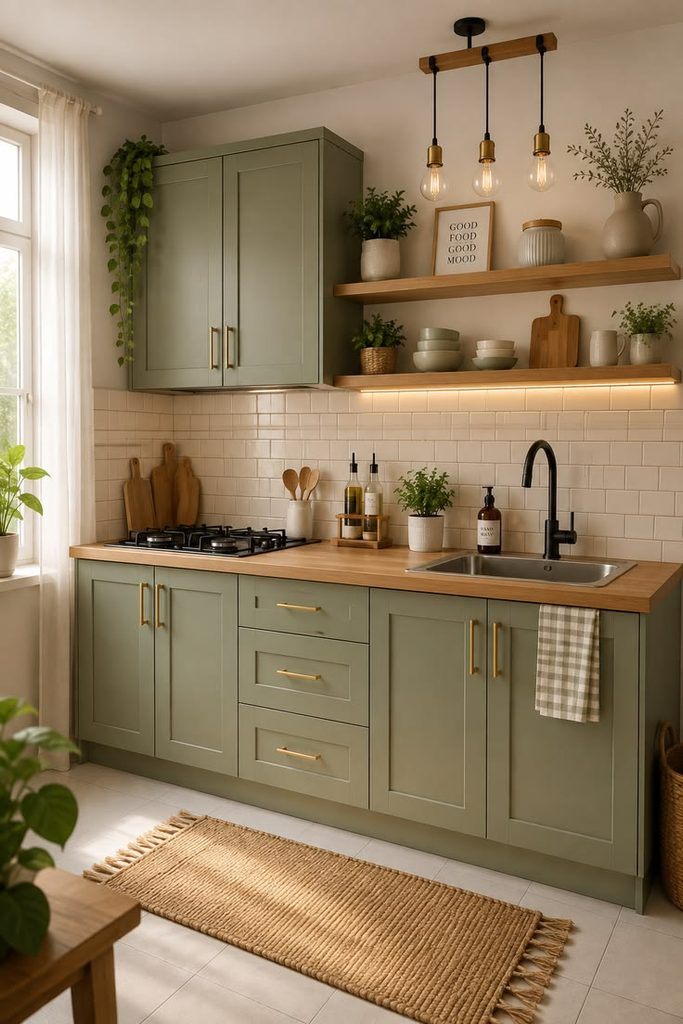
Proposed kitchen concept. Sage cabinets, butcher block counters, open shelving styled and ready. Guests who planned to eat out end up cooking in. That is the mark of a space that was actually designed.
The $60K renovation reserve exists to deliver exactly this. A space guests photograph, share, and book again. This is what turns a unit into a calendar
THE ASSET Residential unit | Honolulu, HI Ultra-luxury finish | Tenant profile: Girls’ trips, bachelor parties, families with kids, party groups — sleeping 3-6, 3 queen beds
THE STRUCTURE
| Capital Ask | Up to $550K |
| Acquisition | $490K or less (listed price) |
| Reno Reserve | $60K (ceiling, not floor) |
| Deployed Capital | Receipt-verified — any unspent reno budget seeds the operating reserve before participation begins |
| Split | Flat 80/20 in funder’s favor |
| Step-down | None. 80/20 the entire way through. |
| Structure | Revenue Participation Agreement — not a loan, not equity |
| Recourse | Zero personal recourse |
THE NUMBERS
| Line Item | Conservative | Realistic | Optimistic |
|---|---|---|---|
| Occupancy | 60% | 70% | 80% |
| Nights/Month | 18 | 21 | 24 |
| Gross Monthly | $17,982 | $20,979 | $23,976 |
| GET (4.712%) | ($847) | ($988) | ($1,130) |
| TAT (13.25%) | ($2,382) | ($2,780) | ($3,177) |
| Operating Costs | ($2,000) | ($2,000) | ($2,000) |
| Maintenance Reserve | ($750) | ($750) | ($750) |
| Operating Reserve (accumulation) | ($1,678) | ($1,678) | ($1,678) |
| Net Available (Accumulation) | $10,325 | $12,783 | $15,241 |
| Net Available (Post-Reserve Cap) | $11,003 | $14,461 | $16,919 |
| Funder 80% (Accumulation) | $8,260 | $10,226 | $12,193 |
| Funder 80% (Post-Reserve Cap) | $8,802 | $11,569 | $13,535 |
| Operator 20% (Accumulation) | $2,065 | $2,557 | $3,048 |
| Operator 20% (Post-Reserve Cap) | $2,201 | $2,892 | $3,384 |
| Recovery Target | $605,000 | $605,000 | $605,000 |
| Year 1 Recovery | $99,120 | $122,712 | $146,316 |
| Remaining After Year 1 | $505,880 | $482,288 | $458,684 |
| Estimated Recovery Timeline | ~70 months (~5.8 years) | ~54 months (~4.5 years) | ~46 months (~3.8 years) |
12-month reserve target: $20,136 Monthly contribution: $1,678 (pauses once target reached, resumes if drawn below threshold)
Estimated combined tax drag pending CPA confirmation. Applied proportionally before 80/20 split
MAINTENANCE RESERVE
A $750 per month maintenance reserve is deducted from net rental income prior to distribution and held in a dedicated reserve account. This reserve is capped at $9,000 annually. Once the cap is reached, the monthly $750 deduction ceases and full net income flows to the 80/20 split until the reserve is drawn down below the cap threshold — at which point monthly contributions resume until the cap is restored.
This reserve is separate from the operating reserve, which covers fixed carrying costs during vacancy periods and is funded independently. Reserve funds are used exclusively for asset maintenance, repair, and condition preservation— appliances, fixtures, plumbing, and structural elements within the unit. Any expenditure from the reserve exceeding $5,000 is documented and reported to the funder within 5 business days.
This reserve exists because AirBnB host protection covers guest damage. It does not cover a leaky sink at 2am, a toilet that needs replacing between bookings, or an appliance that dies mid-stay. Those are operator responsibilities. This reserve ensures they never come out of funder distributions or the operator’s personal cut.
Unused reserve funds at agreement termination are retained by the operator.
OPERATING RESERVE
A dedicated operating reserve is maintained for this property to cover fixed carrying costs during periods of reduced or zero occupancy. HOA dues, property taxes, insurance, and fixed utilities do not pause for market disruption, force majeure, or extended vacancy. This reserve ensures they are met in full regardless of what the rental market is doing.
The reserve is sized to cover twelve months of fixed carrying costs — the threshold at which this property can weather a full market shutdown without missing a single fixed obligation or touching funder distributions. A monthly contribution is deducted prior to distribution and held in a dedicated reserve account. Contributions pause once the target is reached and resume only if the reserve is drawn down below the threshold.
Reserve funds are held in a dedicated account separate from operating income and the maintenance reserve. They are used exclusively to cover fixed carrying costs during vacancy periods and are never commingled with distributions, maintenance expenditures, or operator income.
This reserve is not a contingency. It is infrastructure. The difference between an operator who planned for disruption and one who didn’t shows up exactly when the market stops cooperating.
WHY FLAT 80/20 IS BETTER FOR YOU
No step-downs. No moving parts. No watching your percentage erode as recovery approaches. You know exactly what you’re getting every single month from day one. The structure doesn’t get more complex as it matures — it just keeps paying.
WHY THIS DEAL EXISTS
This isn’t a mid-tier consolation prize. It’s the proving ground.
The Ilikai is where a capital partner gets to see the operator at real scale — real numbers, real distributions, real asset condition — before deciding whether $7.13 million makes sense. The philosophy, structure, and standard of execution are identical across every Hale Hibiscus asset. Same reporting. Same receipts-backed deployment. Same operator who answers the phone when something breaks.
What’s different here is the guest. This asset is built for the group that wants to celebrate something — girls’ trips, bachelor parties, families who want privacy and a luxury experience without the sterile formality of a hotel. Three queen beds, sleeping up to six, at $333 per bed per night. That guest profile fills calendars. And a full calendar is what makes your 80% land on time every month.
The capital partner who does this deal isn’t settling. They’re being strategic. They’re buying a front-row view of the operator at meaningful scale, with returns that matter, in one of the most resilient short-term rental markets in the country — and they’re positioning themselves to be the obvious choice when the flagship conversation opens.
OPERATOR COMMITMENTS
- Monthly reporting within 5 business days of close
- Monthly distributions within 10 business days
- 24-hour response for urgent maintenance
- 5-business-day notice for any vacancy anticipated to exceed 30 days
- Ultra-luxury asset condition maintained at all times
- Audit rights with 10 business days notice
FAQs –
“I’ve never done a revenue participation agreement before.”
Most people haven’t — it’s not a common structure outside of institutional real estate. But the concept is straightforward. You’re not a lender, so there’s no debt instrument. You’re not an equity partner, so there’s no ownership complexity. You participate in a defined percentage of net rental income until your capital is recovered. Clean in, clean out. No personal recourse, no ongoing liability, no board seat. You’re a revenue participant, not a co-owner.
“Short-term rental feels riskier than long-term. How do you protect against vacancy?”
Two things. First, the asset is priced and positioned for a guest profile that doesn’t cancel when things get tight. At $999 per night, you’re not attracting discretionary budget travelers. You’re attracting people who choose Honolulu for a reason and choose ultra-luxury because that’s simply how they travel. Second, the RPA is structured on net rental income. If the unit is vacant, there’s no distribution — the operator is not drawing from reserves to pay a manufactured return. What you see is what’s actually happening. Transparency over optics, every time.
“What’s the STR legal status?”
The Ilikai complex has a well-documented history of permitted short-term rentals and is one of the most recognized STR-friendly buildings in Honolulu. STR permitting has been confirmed at the building level. Unit-specific permit status and CC&R compliance will be formally verified during due diligence, and that documentation will be made available to any capital partner who reaches the agreement stage. We don’t build deals on assumptions — and we don’t ask you to fund one on them either.
“How do I know you’ll actually operate the way you say?”
You don’t. Not on paper. That’s a fair answer and the operator will give it to you directly. What you do have is a deal structured at a size where the operator’s performance is genuinely visible — reporting, distributions, communication, maintenance response, asset condition — over the first year. At $525K, the stakes are real enough that the operator’s systems either hold or they don’t. You’ll know. And when the flagship conversation comes, you won’t be evaluating a stranger. You’ll be evaluating a track record you witnessed firsthand.
“Why not just get a traditional mortgage?”
The operator could. But a traditional mortgage puts debt service ahead of everything — including asset quality, operator flexibility, and the capital partner relationship. The RPA structure means the operator’s obligation is tied directly to the asset’s performance. If the asset performs well, you recover faster. If it underperforms, there’s no debt obligation extracting from the operation regardless of how the unit is doing. The structure keeps both parties on the same side of the table. That’s not an accident. It’s a deliberate design choice.
“Why is this the mid opportunity and not the flagship?”
Because the flagship is a $7.13 million ask on a penthouse asset targeting C-suite visitors and ultra-high-net-worth travelers. The Ilikai mid opportunity is the asset that proves the operator’s philosophy at meaningful scale before that conversation happens. It’s not a consolation prize. It’s a strategic entry point into a portfolio with a very clear ceiling — and the capital partner who comes in here first is positioning themselves to be the obvious choice when the flagship opens
“What’s your exit if this doesn’t work?
Three paths. You recover your full capital through distributions and the RPA terminates — you’re whole, I keep the asset free and clear.
- If I sell the asset before you’re fully recovered, you’re made whole from proceeds before I see a dollar of gain.
- Or if I refinance, same thing — outstanding balance retires before I benefit.
- Every exit path makes you whole first. That’s not negotiable and it’s written into the agreement.
If you’re the kind of person who wants to understand how someone operates before you commit at scale – this deal was structured for you.
This page is a private, confidential summary for qualified capital consideration only. Not a securities offering. Full legal documentation prepared by counsel prior to closing.